2025–2026 Executive Data Summary (Quick Reference)
- China Titanium Sponge Self-Sufficiency Rate (2025–2026): >85% overall (>92% in industrial Grade 1/Grade 2 sponge; rapid import substitution in aerospace Grade 0 sponge).
- Total Installed Capacity (Q1 2026): 440,000 metric tons/year (up +100,000 t/y from 340,000 t/y in 2025).
- Key Producers Driving Expansion: Integrated TiCl4/TiO2 giants (Tianyuan Haifeng, Lomon Billions) + aerospace-focused leaders (Baoti, Pangang, Chaoyang Jinda, Wanhao Titanium).
- 2026 Benchmark Sponge Price: ~$6,080/ton (99.6% purity Grade 1); structural divergence between tight Grade 0 (O <= 0.04%) aerospace feedstock and oversupplied Grade 1 (O <= 0.06%) chemical feedstock.
By the end of Q1 2026, China’s annual titanium sponge capacity punched through 440,000 metric tons. A year ago it was 340,000. That 100,000-ton jump did not arrive gradually — it concentrated in three provinces, five companies, and one shared bet.
This is not a simple overcapacity story. Behind the surplus is a calculated wager: that aerospace will recover, that clean energy infrastructure will scale, and that tightening export controls will hand domestic producers pricing power.
The question is whether the bet pays off.
Where the 100,000 Tons Came From
The numbers are straightforward. China’s monthly titanium sponge output in January 2026 was 23,800 tons, up 0.42% month-on-month. But capacity and output are two different things.
New capacity falls into three tiers:
Tier 1: TiO2 producers moving upstream. Tianyuan Haifeng added 100,000 t/y of chloride-process TiO2 capacity in Yibin, doubling its total to 200,000 tons. TiO2 producers already control titanium tetrachloride (TiCl4) feedstock, so extending into sponge production carries minimal marginal cost.
Tier 2: State-owned and leading private sponge producers expanding. Key players like Baoti, Pangang, and private leaders including Wanhao Titanium (万豪钛业) have scaled up rapidly. Under Beijing’s critical mineral policy, China’s titanium self-sufficiency rate exceeded 85% by 2025, with major capacity directed at military and aerospace-grade demand (especially high-purity Grade 0 sponge).
Tier 3: Small private mills chasing the cycle. These operators entered after seeing strong sponge prices in 2024. Equipment is mostly Kroll process, product is typically Grade 1 or Grade 2 sponge, and the primary market is chemical processing, titanium sheets & plates, and general industrial use.
The strategies differ sharply. Tier 1 is pursuing economies of scale. Tier 2 is defending high-end barriers to entry. Tier 3 is gambling on price.

Where Prices Are Heading
Average sponge pricing sits at $6,080/ton (99.6% purity), up 10.5% year-on-year. That seems counterintuitive. Why would prices rise during a capacity glut?
Three reasons:
-
The aerospace-chemical price gap is widening. Grade 0 sponge (oxygen content 0.04% max) remains tight and prices hold firm. Grade 1 (0.06% max) is abundantly available and under pressure. The “overcapacity” is structural — low-end surplus, high-end shortage.
-
Export scrutiny is increasing. China has not formally placed titanium on an export license list, but critical metals export reviews have tightened steadily through 2025-2026. Uncertainty among overseas buyers is pushing spot premiums higher.
-
Chemical-sector demand is lagging. Industry analysis from SMM indicates price pressure across the full value chain. The 2026 outlook depends on aerospace recovery and renewable energy infrastructure spending actually materializing. Chemical-grade sponge consumption has underperformed expectations.
The effect on Grade 5 (Ti-6Al-4V) pricing is particularly nuanced. Alloying elements — aluminum and vanadium — have remained stable in price, but sponge cost as the base feedstock transmits directly into forgings and bar stock pricing. GR5 bar ex-works prices dropped roughly 5% year-on-year.
What Export Controls Actually Mean in Practice
On paper, titanium did not make China’s 2026 export license blacklist. In practice, however:
- Customs review timelines have stretched from 3 days to 7-10 days
- Bulk shipments (single batches above 5 tons) now require additional end-user certificates
- Dual-use grades (TA15, TC4/Grade 5 aerospace specification) face the strictest scrutiny
The impact hits small and mid-size trading companies hardest — they lack established overseas customer relationships needed to produce end-user documentation. For supply chain platforms with long-term contract relationships and stocking programs, the impact is manageable but compliance costs have risen.
Signals from the Ground in Titanium Valley

We see this playing out firsthand.
Starting in March, utilization rates at smaller local mills dropped noticeably. below 85%. The reason is simple: chemical processing orders have dried up, and aerospace orders are out of reach — without NADCAP certification, these mills cannot enter Tier-1 supply chains.
But the inquiry mix is shifting. In Q1 this year, inquiries from Southeast Asia and the Middle East for titanium tubes and titanium sheets and plates rose noticeably. These markets are absorbing demand that spills over from China’s tightening export regime. Buyers there still want Chinese material — the process has just become more complicated, and they need suppliers who can handle the compliance paperwork.
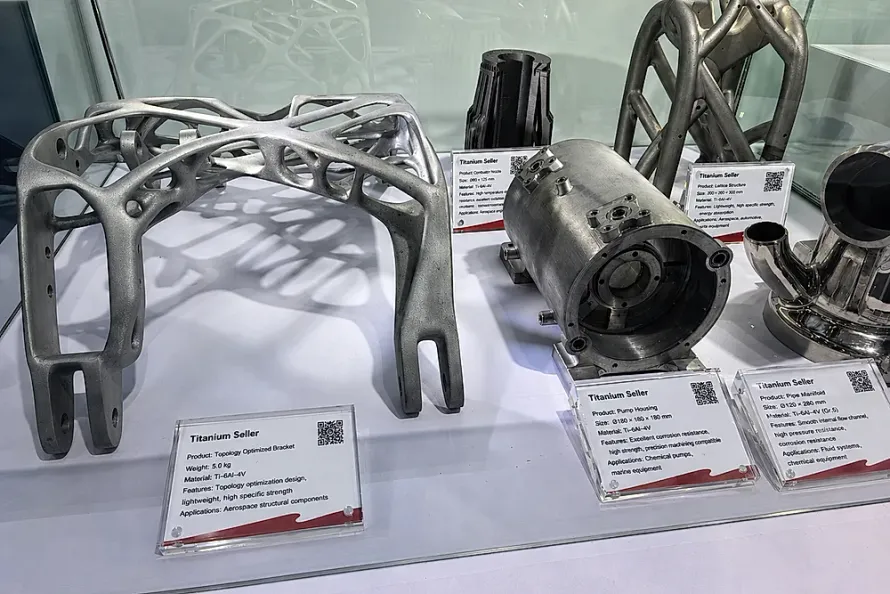
Another signal worth watching: customers have started asking about Ti-6Al-4V wire for orthodontic applications. This suggests additive manufacturing and medical end-markets are beginning to penetrate the traditional titanium mill product supply chain.
“Upstream is oversupplied, but downstream demand is fragmenting in new directions. Suppliers who can deliver both conventional bar stock and emerging wire products are actually gaining ground, not losing it.” — Darren, Supply Chain Director
Procurement Recommendations by Buyer Profile
If you are an aerospace Tier-2 quality engineer:
- Secure your Grade 0 sponge sources now. The surplus is in low-end material; aerospace-grade supply remains tight
- Require oxygen content test reports traceable to the heat number on every sponge batch your supplier provides
If you are a chemical plant engineer:
- This is a buying window. Grade 1 sponge is plentiful, and raw material costs for titanium heat exchanger tubes and titanium plate are at a two-year low
- Do not accept material without a Mill Test Certificate, regardless of how attractive the price looks
If you are a multinational procurement director:
- Build a dual-source strategy. Uncertainty around Chinese export controls is rising — Japanese producers (Toho, Osaka Titanium) and Kazakhstan offer viable supplementary sourcing
- For Chinese suppliers, prioritize platform companies with long export track records and comprehensive quality inspection systems
Conclusion
440,000 tons per year is not the ceiling. If the aerospace recovery materializes in the second half of 2026, this capacity will be absorbed. If it does not, Tier 3 mills face shutdown or consolidation before year-end.
Regardless of which scenario plays out, the structural shift is already underway: the price gap between high-end and low-end material is widening, compliance requirements are tightening, and end-market demand is fragmenting. The suppliers that survive this cycle will not be the ones with the most capacity — they will be the ones with the strongest quality control and compliance capabilities.
Related Products & Services
- Service → Stocking Programs — Lock in GR5 raw material pricing ahead of sponge cost volatility
- Product → Titanium Rods — GR5/GR2/TA15 grades, stock and custom lengths
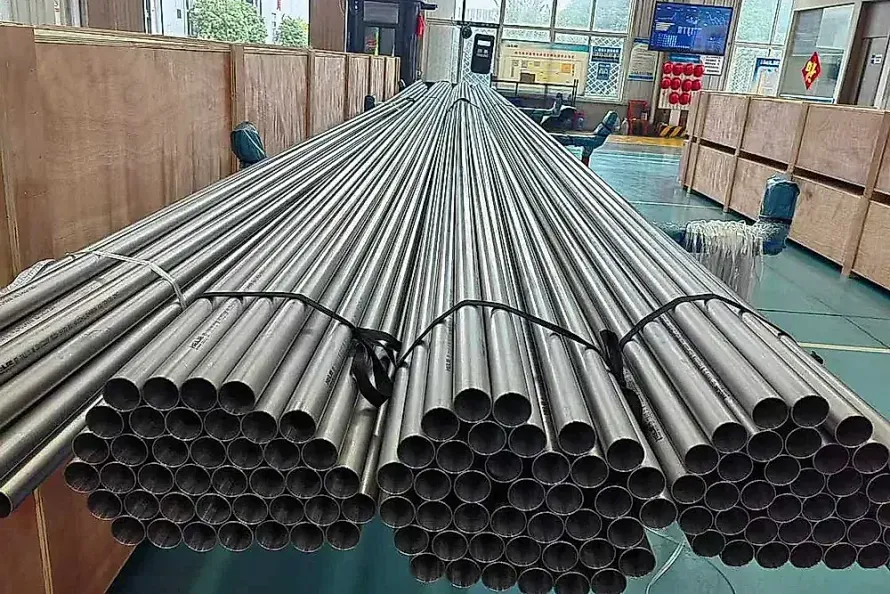
- Product → Titanium Tubes — Chemical and aerospace grades, both drawn and welded
Related Articles:
- US Titanium Act: What It Means for Global Buyers
- Middle East Desalination Boom: What $250B Means for Titanium Tubes
- Aerospace Titanium Supply Chain Is Being Reshaped
About: Titanium Seller is a supply chain platform based in Baoji, China’s Titanium Valley.